Vacation Rental Insurance on Hilton Head: What Owners Need
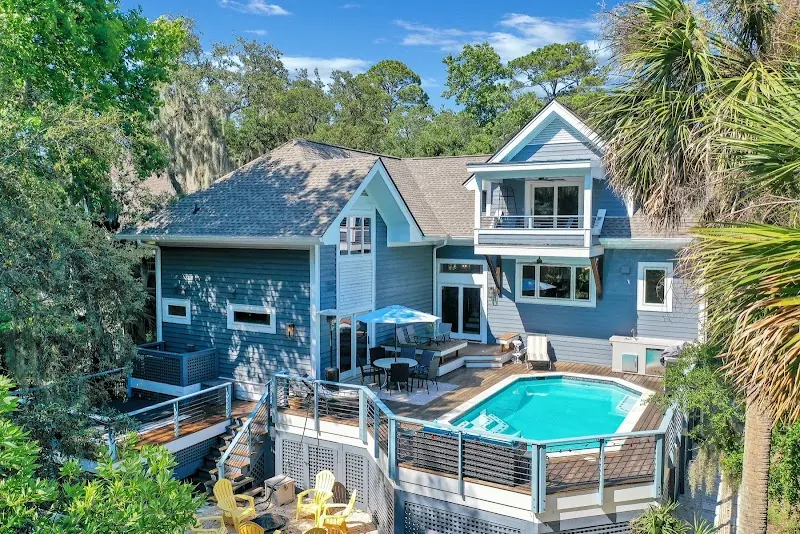
A homeowners policy is written for a home you live in, and it may not pay a claim tied to paying guests. A Hilton Head vacation rental needs cover written for renting: liability when a guest is hurt, the building and furnishings in rental use, and the rent lost while it’s being repaired.
What a Homeowners Policy Leaves Out
A homeowners or renters policy isn’t designed to cover accidents that come from renting, and the insurer may deny the claim. A friend who trips on your stairs is usually covered. A paying guest who trips on them may not be, because renting the whole house to guests can look to an insurer like running a small hotel. These are the gaps that matter on a rental:
Liability for guest injuries
A fall on the stairs, a pool or hot tub accident, a bike crash on a borrowed bike.
Damage by guests
Broken furniture, a burned counter, a flooded bathroom, or worse.
Lost rent
The bookings you lose while a covered loss, like a storm or a fire, is repaired.
Furnishings you supply
Beds, linens, kitchenware, TVs, beach gear and bikes left for guests.
Get the Hilton Head home insurance checklist
Wind, flood and homeowners cover, the 30-day flood wait, condo policies, golf carts and rentals. Free, by email, in plain English.
Short-Term Rental Insurance in South Carolina
An endorsement. For a home you live in and rent now and then, some insurers will add rental use to the homeowners policy. Get it in writing.
A landlord or rental dwelling policy. For a home rented regularly. These usually cover the building, the owner’s contents and liability, and can add lost rent.
A short-term rental policy. Written for nightly and weekly rentals, usually with liability for guests, damage by guests and lost bookings built in.
Whichever you choose, tell the insurer how many nights a year it’s rented and whether you also use it. Don’t count on a booking site’s host protection in place of a policy: read what it leaves out. An umbrella policy can add liability on top. On Hilton Head a rental also needs a Town permit: see short-term rental permits on Hilton Head.
Wind and Flood on a Second Home
None of the policies above covers flood, and on the island many leave out wind and hail. A rental needs those as separate policies, and both treat a second home differently from a home you live in:
Wind pool: actual cash value. The South Carolina wind pool offers replacement cost only on a principal residence, so a rental’s wind claim is paid at what the damaged part was worth. See the South Carolina wind pool.
Federal flood: a $250 surcharge. A federal flood policy on a home that isn’t your primary residence carries a $250 yearly surcharge, against $25 on a primary residence, and its renewals can rise up to 25% a year instead of 18%. See flood insurance in South Carolina.
Lost rent after a storm. Check which policy pays lost bookings after a hurricane. A flood policy doesn’t pay lost rent.
Renting Out a Villa or Condo
In a villa or condo building, the owners’ association usually insures the building and common areas, and each owner insures the inside of the unit, the furnishings and their own liability. Ask the association for its master policy’s declarations page and deductible, and whether the association can charge owners a share of a big claim. Many associations also have rules on renting, from minimum stays to guest registration. A rental company can say what it expects an owner to carry: see Hilton Head property management companies.
Frequently Asked Questions
Updated
Does homeowners insurance cover a vacation rental?
Often not. A homeowners policy isn’t designed for accidents that come from renting, and the insurer may deny a claim when a paying guest is hurt or the house is damaged during a rental.
What insurance do I need for a short-term rental in South Carolina?
Cover written for renting: liability for guest injuries, the building and furnishings in rental use, damage by guests and lost rent. That can be an endorsement, a landlord policy or a short-term rental policy, plus separate flood cover and, on the coast, often a separate wind policy.
Does the South Carolina wind pool insure a vacation rental?
Yes, if the home qualifies, but its replacement cost option is only for a principal residence, so a rental’s wind claim is paid at actual cash value.
Is flood insurance more for a second home?
Yes. A federal flood policy on a home that isn’t your primary residence carries a $250 yearly surcharge, against $25 on a primary residence, and its renewals can rise up to 25% a year.
Do villa and condo owners who rent need their own policy?
Yes. The association usually insures the building, and each owner insures the inside of the unit, the furnishings and their own liability, with rental use declared.