How Much Is Flood Insurance in SC? A Hilton Head Guide
There’s no single price. Since 2021 FEMA prices every federal flood policy building by building, from its distance to water, its height and what it would cost to rebuild. On Hilton Head every federal policy gets a 25% discount, and a new one usually takes 30 days to start.
How Much Is Flood Insurance in SC? What Sets the Price
Most flood policies on the coast come from the National Flood Insurance Program, which FEMA runs. Since FEMA’s Risk Rating 2.0 took effect in 2021, the flood zone alone no longer sets the price. Two houses on the same street can pay very different amounts. These are the things that move it:
Distance to water
How close the building sits to the ocean, the sounds, tidal creeks and marsh, and which kinds of flooding can reach it.
Ground and first-floor height
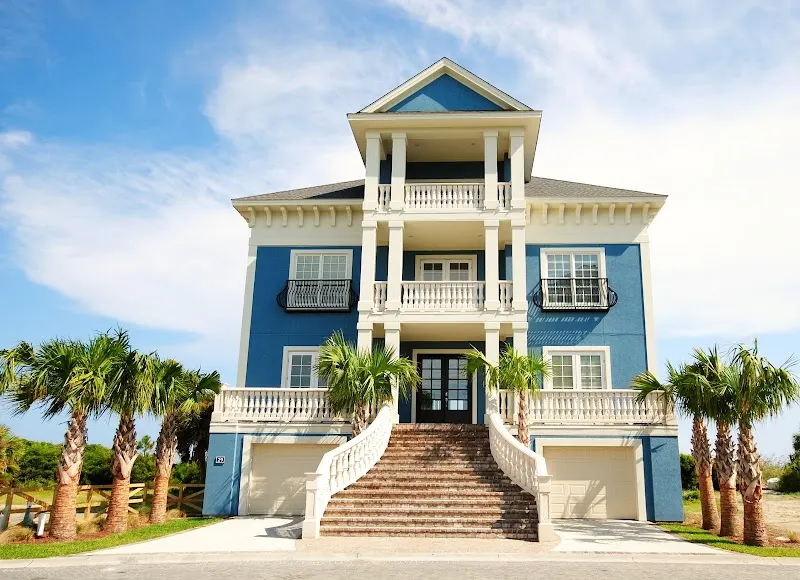
How high the ground is, and how high the lowest living floor sits above it. A raised house usually pays less.
Foundation and build
Slab, crawlspace or pilings, the number of floors, how it’s built, and whether a ground-level garage has flood vents.
Cost to rebuild
A bigger, costlier house to replace means a bigger possible claim, so the price goes up with it.
A 25% discount on the island. The Town of Hilton Head Island is a Class 5 community in FEMA’s Community Rating System, which takes 25% off every property owner’s federal flood policy.
An elevation certificate is optional. FEMA works out the first-floor height itself, but if you have a certificate it uses whichever height is better for you, so it can lower the price.
Increases are capped. When a renewal goes up, most policies can rise no more than 18% a year until they reach the full price. Second homes and other non-primary residences can rise up to 25% a year.
For a price on one address, ask the agency that writes the homeowners policy, or one of the insurance agencies on Hilton Head. Private flood insurers write policies too, sometimes with higher limits.
Get the Hilton Head home insurance checklist
Wind, flood and homeowners cover, the 30-day flood wait, condo policies, golf carts and rentals. Free, by email, in plain English.
Hilton Head Flood Zones and the Flood Zone Map
Low risk
Outside the mapped floodplain. Flood insurance is optional, and usually costs less.
Moderate risk
A 0.2% chance of flooding in any year.
High risk
A 1% chance of flooding in any year. Lenders require flood insurance here.
High risk, with waves
The coastal zone where storm waves add to the flooding. Lenders require flood insurance here too.
Shallow flooding
Sheet flow or ponding, usually one to three feet deep.
FEMA’s current flood maps for Hilton Head took effect on March 23, 2021, the first redraw since 1986. To find the zone for one address, use the Town of Hilton Head Island’s Flood Hazard Zone Search, or call the Town’s floodplain administrator on (843) 341-4687 about the map, elevation certificates and past flooding at a property. In Bluffton and the rest of Beaufort County, look the address up on FEMA’s Flood Map Service Center.
If you have a mortgage from a federally regulated or insured lender and the building is in an A or V zone, the lender will require flood insurance. Outside those zones it’s your choice, and anyone in the Town can buy it. Which streets flood at the highest tides, and how often, is on Hilton Head flooding and king tides.
What a Federal Flood Policy Pays
Up to $250,000
The structure, its electrical and plumbing, the furnace and water heater, built-in appliances and permanent flooring.
Up to $100,000
Furniture, clothes and other belongings, paid at actual cash value: what they were worth, not what new ones cost.
Wind, and much below the lowest floor
Storm wind is a separate policy. In a basement or below a raised house, most belongings aren’t covered.
Homeowners policies don’t cover flood, so this is a policy of its own. A house worth more than $250,000 to rebuild can add an excess or private flood policy on top. In a condo or villa building the association usually insures the building, and each owner insures the inside of the unit and its contents. Wind and hail are covered on the South Carolina wind pool.
The 30-Day Wait
A new federal flood policy usually starts 30 days after you buy it, so it can’t be bought once a storm is in the forecast. The exception is a purchase tied to a loan: buy the policy at closing and it starts with the loan, with no wait. Hurricane season runs from June 1 to November 30, so the time to buy or check a flood policy is spring. The season itself is covered on hurricanes on Hilton Head.
Frequently Asked Questions
Updated
How much is flood insurance in South Carolina?
It depends on the building. FEMA prices each federal flood policy from the home’s distance to water, the height of its lowest floor, its foundation and what it would cost to rebuild, so two houses on one street can pay very different amounts. Ask an agent for a quote on the exact address.
Is flood insurance cheaper on Hilton Head Island?
Yes, by 25%. The Town of Hilton Head Island is a Class 5 community in FEMA’s Community Rating System, which takes 25% off every property owner’s federal flood policy.
How do I find my flood zone on Hilton Head?
Use the Town of Hilton Head Island’s Flood Hazard Zone Search, or call the Town’s floodplain administrator on (843) 341-4687. The current FEMA maps took effect on March 23, 2021.
Do I need flood insurance on Hilton Head?
Your lender will require it if the building is in an A or V flood zone and the mortgage is federally backed. Outside those zones it’s optional, but homeowners policies don’t cover flooding.
How long does flood insurance take to start?
Usually 30 days. A policy bought at closing as part of a home loan starts with the loan, with no wait.
How much does a federal flood policy pay?
Up to $250,000 for the building and $100,000 for contents. Contents are paid at actual cash value, and an excess or private policy can add more.
Do I need an elevation certificate to buy flood insurance?
No. FEMA works out the first-floor height itself, but if you have a certificate it uses whichever height is better for you, which can lower the price.